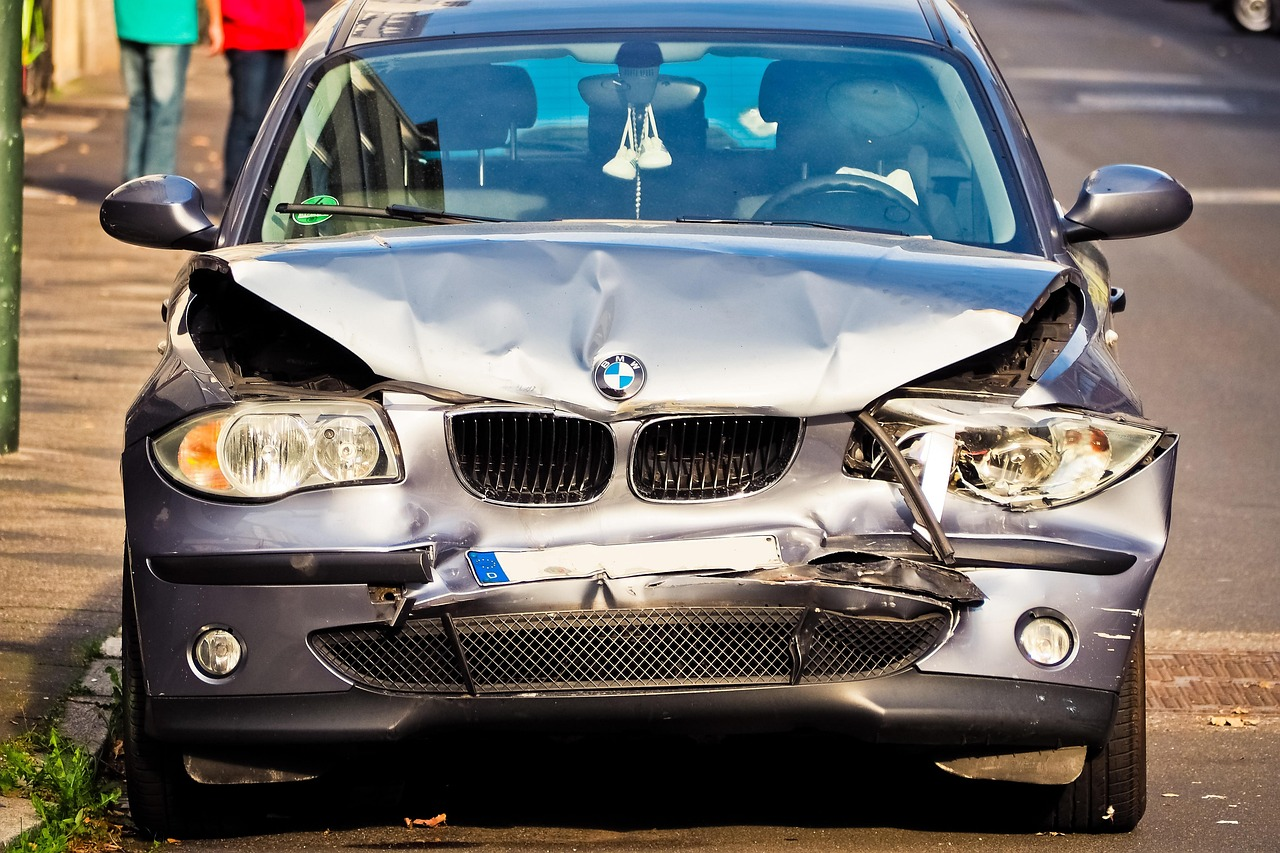
A car accident can become more complicated when the driver who caused the crash does not have enough insurance to cover your injuries. In some cases, the at-fault driver may have no insurance at all. In others, the driver’s liability limits may be too low to cover the losses caused by a serious accident. This is where uninsured motorist (UM) and underinsured motorist (UIM) coverage can become important. These types of coverage may provide a way to seek compensation for certain bodily injury losses through your own automobile insurance policy.
Understanding how UM and UIM claims work can help you recognize what coverage may be available after a Colorado car accident. If you are unsure how to proceed with an insurance claim, a car accident lawyer can review your circumstances and explain your options.
1. What Is Uninsured Motorist Coverage?
Uninsured motorist coverage, commonly called UM coverage, is designed to help when an accident is caused by a driver who does not have applicable automobile insurance. Colorado’s General Assembly explains that UM/UIM coverage can provide benefits for bodily injury losses caused by a hit-and-run driver, an uninsured driver, or an underinsured driver.
For example, if another driver causes a serious collision but has no liability insurance, your own UM coverage may provide an avenue for pursuing covered bodily injury losses, subject to the terms and limits of your policy.
2. What Is Underinsured Motorist Coverage?
Underinsured motorist coverage, or UIM coverage, can become relevant when the at-fault driver’s insurance exists but is not enough to cover the injured person’s losses. For example, suppose another driver’s liability policy has limits that are lower than the damages associated with your injuries. Depending on your policy and the circumstances, UIM coverage may provide additional protection.
Colorado describes an underinsured vehicle as one where the applicable bodily injury liability coverage is less than the insured’s UM/UIM coverage limits.
3. What Is the Difference Between UM and UIM Coverage?
The basic difference is whether the at-fault driver has applicable insurance. Uninsured motorist coverage may apply when the responsible driver has no insurance or in certain hit-and-run situations. Underinsured motorist coverage may apply when the responsible driver has insurance, but the available liability limits are insufficient in relation to the applicable losses and coverage.
Both types of coverage are generally intended to address bodily injury losses rather than simply replacing the other driver’s property-damage coverage.
4. Is UM/UIM Coverage Required in Colorado?
Colorado law generally requires automobile liability policies to include uninsured motorist coverage unless the named insured rejects that coverage in writing. The Colorado General Assembly also explains that policyholders may choose lower coverage limits or reject the coverage as permitted by law.
Because insurance policies can differ, it is important to review your own policy to determine what coverage you actually have. Do not assume that you have a particular level of UM/UIM protection without checking the policy documents.
5. When Can You Make an Uninsured Motorist Claim?
A UM claim may become relevant when an uninsured driver causes an accident that results in covered bodily injuries. A hit-and-run collision can also create questions about UM coverage. Colorado law contains provisions addressing situations in which an alleged at-fault driver cannot be located and certain requirements for treating the driver as uninsured for purposes of UM coverage are met.
If you are involved in a hit-and-run crash, report the incident and preserve any available evidence, including photographs, witness information, surveillance footage, and police documentation.
6. When Can You Make an Underinsured Motorist Claim?
A UIM claim may be considered when the at-fault driver has liability insurance, but the available limits may not be sufficient to cover the bodily injury losses involved. For example, serious injuries may result in substantial medical expenses, lost income, and other damages that exceed the at-fault driver’s policy limits.
Whether additional UIM benefits are available depends on the applicable insurance policies, coverage limits, the amount already paid by the at-fault driver’s insurer, and other circumstances.
7. What Damages May Be Covered?
UM/UIM coverage generally focuses on bodily injury losses. Depending on the applicable policy and circumstances, a claim may involve losses such as:
Medical expenses
Future medical treatment
Lost income
Reduced earning capacity
Physical pain
Other injury-related losses
Colorado’s official guidance specifically notes that UM/UIM coverage pays for the insured’s bodily injury losses and does not cover damage to the insured’s vehicle. Property damage may instead involve other applicable insurance coverage.
8. You Still Need to Establish the Accident and Your Injuries
Having UM/UIM coverage does not mean that every claim is automatically paid. You may still need evidence showing that the accident occurred, another driver was responsible, and you suffered covered injuries and losses.
Useful evidence can include:
Police or crash reports
Accident-scene photographs
Witness statements
Dashcam or surveillance footage
Medical records
Medical bills
Employment records
Vehicle and accident documentation
Insurance policy information
Keeping this information organized can help when the insurance company evaluates your claim.
9. Your Own Insurance Company May Investigate the Claim
When you make a UM or UIM claim, your own insurance company may investigate the circumstances of the accident and your injuries. The insurer may review evidence concerning liability, medical treatment, damages, and the available insurance coverage.
This does not mean that every claim will be disputed, but you should still provide accurate information and keep copies of documents submitted to the insurer. If the insurance company questions your injuries, liability, coverage, or the amount of your losses, a car accident lawyer can help you understand how to respond.
10. Do Not Assume the Other Driver's Policy Is Enough
After an accident, it can be easy to focus only on the at-fault driver’s liability insurance. However, if the available liability limits are insufficient, your own UM/UIM coverage may become important. This is particularly relevant when an accident results in serious injuries and substantial losses.
Reviewing all potentially applicable policies can help determine what sources of coverage may be available.
11. What Does an Uninsured Motorist Attorney Do?
An uninsured motorist attorney can review the accident, applicable insurance policies, medical documentation, and other evidence related to a UM or UIM claim.
Depending on the circumstances, legal assistance may involve communicating with insurers, reviewing coverage questions, evaluating documented losses, and addressing disputes over liability or the value of the claim. The specific steps will depend on the facts of the accident and the language of the insurance policies involved.
12. When Should You Contact a Car Accident Lawyer?
You may want to speak with a car accident lawyer if the at-fault driver has no insurance, does not have enough coverage, the accident was a hit-and-run, or your injuries and losses are significant.
Legal guidance can also be useful when an insurer disputes your UM/UIM claim or you are unsure how your policy applies to the accident.
Protecting Your UM/UIM Claim
After an accident involving an uninsured or underinsured driver, preserve as much relevant information as possible. Keep copies of the crash report, medical records, bills, insurance documents, photographs, witness information, and communications with insurers.
Most importantly, review your own policy to understand the UM/UIM coverage that may be available to you. If you were injured in a Colorado accident involving an uninsured or underinsured driver, 5280 Injury Law can help you understand your potential claim and the insurance options that may apply to your situation.
Frequently Asked Questions (FAQs)
What is uninsured motorist coverage?
Uninsured motorist coverage is insurance protection that may provide compensation for covered bodily injury losses caused by an uninsured or hit-and-run driver, subject to the policy and applicable law.
What is underinsured motorist coverage?
Underinsured motorist coverage may provide additional protection when the at-fault driver’s available bodily injury liability coverage is insufficient to cover the applicable losses.
Is uninsured motorist coverage required in Colorado?
Colorado generally requires UM coverage to be included in automobile liability policies unless the named insured rejects the coverage in writing.
Can I make a UM claim after a hit-and-run?
A UM claim may be available after a hit-and-run when the applicable legal and policy requirements are met. Colorado law contains specific provisions addressing when an unidentified or unavailable driver may be treated as uninsured for UM purposes.
Should I contact a lawyer for an uninsured or underinsured motorist claim?
Consider speaking with a car accident lawyer when your injuries are significant, the available insurance coverage is unclear, the insurer disputes your claim, or you are unsure how to evaluate a UM/UIM settlement.